September 15, 2026 | Business Finance | Banking & Lending | Credit & Underwriting | Leadership & Sales | Channel Insights
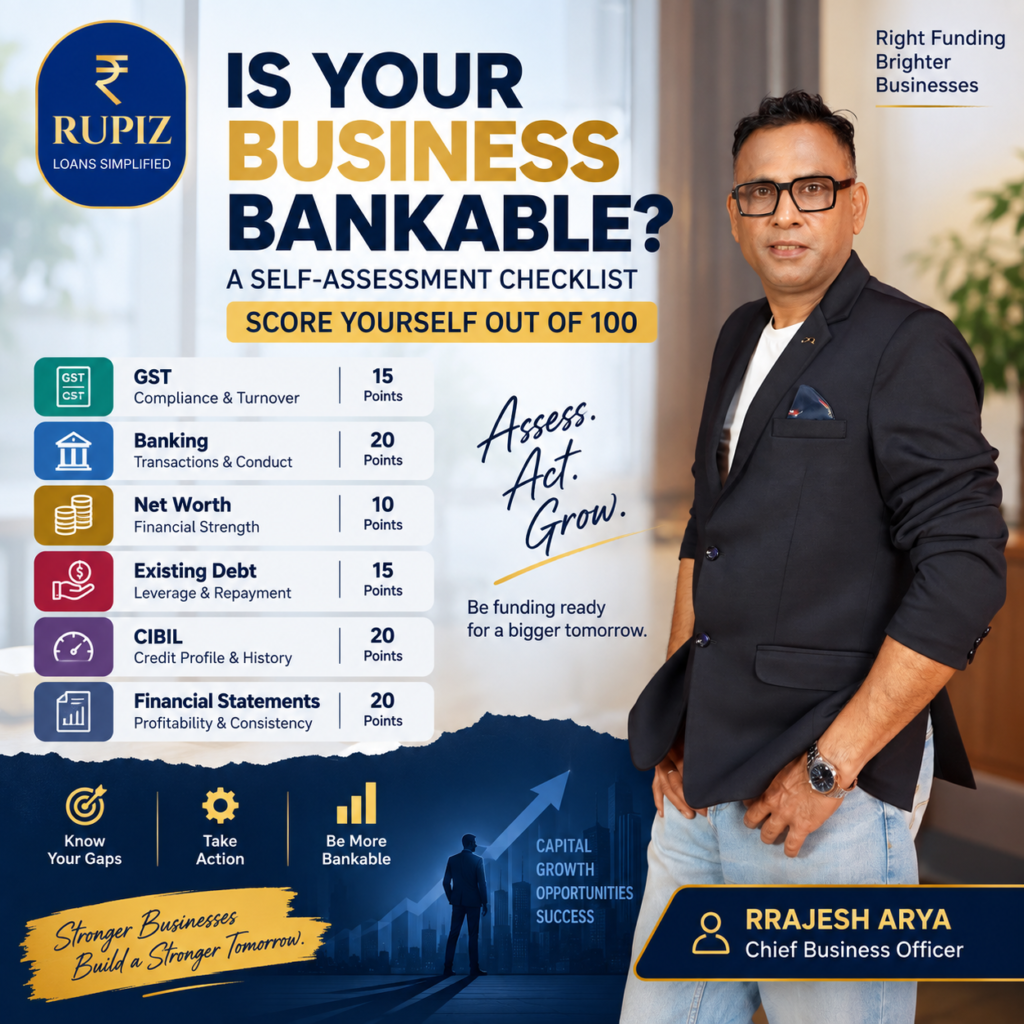
A Practical Self-Assessment Checklist — Score Yourself Out of 100
A profitable business is not automatically a bankable business.
Many entrepreneurs believe that if their business is making money, getting a loan should be easy.
But lenders look beyond profitability.
They want to understand one fundamental question:
“Can this business responsibly take on additional debt and repay it?”
That answer is built from multiple signals — GST compliance, banking behaviour, net worth, existing debt, credit history and the quality of financial statements.
In fact, lenders use credit information and financial data to assess borrowing behaviour, repayment capacity, existing obligations and risk. TransUnion CIBIL’s commercial credit reports, for example, provide lenders with information on credit history, debt build-up, utilisation, delinquency and other credit behaviours.
So before approaching a bank or NBFC, why not assess your own business first?
Here is a simple 100-point Business Bankability Self-Assessment.
The 100-Point Business Bankability Score
1. GST — 15 Points
Your GST data can help demonstrate the scale and consistency of your business operations.
Ask yourself:
☐ Are GST returns filed regularly and on time?
☐ Is reported turnover consistent with your business activity?
☐ Is there a reasonable trend of turnover growth or stability?
☐ Are there significant mismatches between GST, banking and financial statements?
☐ Are there any major compliance issues or unexplained variations?
Scoring:
- 13–15: Strong
- 9–12: Acceptable
- 5–8: Needs attention
- 0–4: High concern
2. Banking — 20 Points
Your bank statement tells a lender a story that financial statements alone may not reveal.
Check your banking behaviour:
☐ Regular business credits
☐ Healthy average balance
☐ No frequent cheque/ECS/EMI bounces
☐ No unexplained large cash transactions
☐ Existing limits are used responsibly
☐ Business collections are routed through identifiable bank accounts
☐ Banking turnover broadly supports reported business turnover
Scoring:
- 17–20: Strong banking profile
- 13–16: Good
- 8–12: Needs improvement
- 0–7: Weak
Banks generally ask MSME borrowers for bank statements along with GST returns, ITRs and financial statements when evaluating loan applications.
3. Net Worth — 10 Points
Net worth is not just about owning property.
It reflects the financial strength of the business/promoters after considering liabilities.
Ask:
☐ Is the business adequately capitalised?
☐ Has net worth grown over the years?
☐ Is promoter contribution meaningful?
☐ Is the business excessively dependent on borrowed money?
☐ Are accumulated losses affecting net worth?
Scoring:
- 9–10: Strong
- 7–8: Healthy
- 4–6: Moderate
- 0–3: Weak
A strong net worth position can improve the overall perception of financial stability, although lender requirements vary by product and borrower profile.
4. Existing Debt — 15 Points
More loans don’t necessarily mean a bad business.
The real question is whether your existing debt is manageable.
Review:
☐ Total outstanding loans
☐ Monthly EMI obligations
☐ Working capital limits
☐ Credit card/business card exposure
☐ Existing unsecured borrowing
☐ Recent loan enquiries
☐ Timeliness of repayments
☐ Whether additional borrowing is genuinely required
Scoring:
- 13–15: Comfortable
- 9–12: Manageable
- 5–8: Stretched
- 0–4: High leverage
Remember:
A lender doesn’t only ask, “How much do you want?”
The lender also asks:
“How much debt can this business comfortably service?”
5. CIBIL & Credit Profile — 20 Points
Your credit profile is one of the most important parts of your bankability.
But don’t look only at the headline score.
Look at the complete credit behaviour.
☐ No significant overdue accounts
☐ No recent serious defaults
☐ No frequent loan applications
☐ Existing loans are being serviced on time
☐ Credit utilisation is controlled
☐ No unexplained adverse credit remarks
☐ Personal and business borrowing behaviour is disciplined
For commercial borrowers, credit assessment can include repayment behaviour, delinquency, debt build-up, utilisation trends and the overall borrowing relationship across lenders.
Scoring:
- 18–20: Excellent
- 14–17: Good
- 8–13: Needs attention
- 0–7: High concern
Important: There is no single CIBIL score that guarantees loan approval. Every lender has its own credit policy.
6. Financial Statements — 20 Points
Your financial statements are the financial language of your business.
Ask yourself:
☐ Are Balance Sheets and P&L statements prepared regularly?
☐ Are financials audited where applicable?
☐ Is profitability consistent?
☐ Is revenue growth supported by actual banking/GST data?
☐ Is EBITDA/PAT reasonably healthy?
☐ Are receivables under control?
☐ Is the balance sheet adequately capitalised?
☐ Can you explain major year-on-year variations?
A lender may typically request financial statements along with GST returns, ITRs and banking information as part of the MSME loan process.
Scoring:
- 18–20: Strong
- 14–17: Good
- 8–13: Needs improvement
- 0–7: Weak
Now Calculate Your Score
| Area | Maximum |
| GST | 15 |
| Banking | 20 |
| Net Worth | 10 |
| Existing Debt | 15 |
| CIBIL & Credit Profile | 20 |
| Financial Statements | 20 |
| TOTAL | 100 |
Your Score: ____ / 100
85–100: FUNDING READY
Your business appears to have a strong foundation for approaching lenders.
That doesn’t guarantee approval, but your overall profile is likely to be better positioned for structured borrowing.
70–84: BANKABLE — WITH ROOM TO IMPROVE
You have a reasonably strong foundation, but strengthening a few areas could improve your funding readiness.
50–69: PROCEED WITH CAUTION
Before applying for additional debt, identify the weaker areas and work on them.
A better-prepared application can be more effective than approaching multiple lenders without addressing underlying gaps.
Below 50: NOT FUNDING READY YET
This doesn’t mean your business cannot get funding.
It means the business may need financial strengthening before taking on additional debt.
The Most Important Lesson
Bankability is not created when you apply for a loan.
It is created months and sometimes years before the application.
Consistent banking.
Clean credit behaviour.
Healthy financial statements.
Controlled leverage.
Tax and GST discipline.
Growing net worth.
Together, these create something far more valuable than a loan application:
LENDER CONFIDENCE.
And that is what every business should aim to build.
At RUPIZ, we believe businesses shouldn’t simply ask:
“Which lender will give me a loan?”
They should first ask:
“How bankable is my business today?”
Because the better prepared the business, the better positioned it can be to approach the right lender and the right funding structure.
Final Thought
Don’t wait for a lender to tell you what’s wrong with your business.
Assess yourself first.
Score yourself out of 100.
And if your score is below where you want it to be, that’s not necessarily bad news.
It gives you a roadmap.
#BusinessFunding #BusinessLoan #MSME #BusinessFinance #CIBIL #GST #WorkingCapital #Lending #Entrepreneurship #RUPIZ


